Refinancing and Restructuring Debt

Most dental practices have debts and loan obligations and some struggle to meet them. Yet, there are ways to overcome these challenges and thrive financially. Refinancing and restructuring debts can really help dental clinic owners manage their finances, but you need to understand how it works and where to begin. Here, we’ll see how refinancing and restructuring debts can benefit your clinic, the steps to start the process, and what you need to know. We’ll also share some tips to help you achieve financial stability and success.
Understanding the Challenges Faced by Dental Practices

Dental clinics face significant financial challenges due to tough competition, rising costs, and evolving industry standards. Keeping up with changing NHS regulations and the shift towards private dental care requires investments in equipment, technology, and staff training. 

On top of this, most dental practice owners need to borrow money to buy or set up their dental practice in the first place.

Moreover, clinics can struggle to retain existing patients and attract new ones amidst fierce competition, necessitating expensive marketing strategies and maintaining patient satisfaction. The high operational costs, including rent, bills, insurance, and staff salaries, further strain clinic finances, compounded by the need for continuous training and adherence to hygiene standards. 
Navigating-debt-financing-1

How to Assess Your Current Financial Situation

Before tackling debt refinancing or restructuring, it’s crucial to get a clear picture of your dental practice’s financial health. This is the foundation for making informed decisions about managing your debt.

  • Gather Your Financial Documents: Start by collecting key financial documents like balance sheets, income statements, and cash flow statements. These will show you your recent performance and give you a snapshot of your practice’s financial health. 
  • Analyse Your Financial Strengths and Weaknesses: Review these documents carefully to identify areas where your practice is doing well and areas that need improvement. Look for trends or patterns that might affect your debt management strategy.
  • Financial Ratios: Measuring Your Practice’s Health: Financial ratios like the debt-to-equity ratio, current ratio, and debt service coverage ratio can tell you a lot about your practice’s financial health. These ratios measure factors like your ability to meet debt obligations, cover short-term liabilities, and manage overall debt levels.
  • Cash Flow Management: Keeping Track of Inflows and Outflows: Understanding your cash flow allows you to proactively manage incoming and outgoing funds. This helps ensure you have enough cash available to cover expenses and debt payments. You will also be able to more easily identify areas you can save money, and where you may need to spend a little more.
  • Get Expert Help: Consider consulting a financial advisor or accountant like Samera with experience in the dental industry. They can help you interpret your financial data, identify areas for improvement, and make informed decisions about debt restructuring and refinancing.
  • Benefits of Understanding Your Finances: By getting a thorough understanding of your practice’s financial situation, you’ll be well-equipped to make smart decisions about debt management. This paves the way for financial success and the long-term stability of your dental practice.
Navigating-debt-financing-2

Click here to read our article on 11 Top tips to manage your cash flow in a crisis

Debt Restructuring vs. Refinancing: Understanding Your Options

When it comes to managing dental practice debt, you have two main options: restructuring and refinancing.  Here’s a breakdown of each strategy:

Debt Restructuring:

  • Think of it as a negotiation: Debt restructuring involves working directly with your existing lenders to modify the terms of your current loans. This could involve extending repayment periods, reducing interest rates, or even forgiving a portion of the debt in exchange for a lump sum payment.
  • Benefits: Restructuring can significantly reduce your monthly debt payments, improving cash flow and freeing up resources for other needs. It can also simplify your debt by consolidating multiple loans into a single one.
  • Considerations: Restructuring may not always be an option, depending on your lender and your financial situation. It’s important to negotiate effectively and have a clear understanding of your desired outcome.

Debt Refinancing:

  • Taking out a new loan to pay off old ones: Debt refinancing involves securing a new loan with more favorable terms than your existing debt. This new loan is then used to pay off your existing ones, resulting in potentially lower interest rates, longer repayment periods, or both.
  • Benefits: Similar to restructuring, refinancing can free up cash flow and simplify your debt management. However, refinancing often comes with additional fees associated with the new loan.
  • Considerations: Qualifying for a new loan may require good creditworthiness. Carefully compare interest rates and fees associated with refinancing to ensure it’s truly beneficial.

Choosing the Right Option:

The best approach for your dental practice depends on your specific financial situation and goals. Consider factors like the interest rates on your existing loans, your creditworthiness, and your desired monthly payment amount. Consulting a financial advisor experienced in the dental industry can help you assess your options and choose the strategy that best suits your needs.
Navigating-debt-financing-3

The Potential Impact on Cash Flow and Profitability

When thinking about refinancing and restructuring debt, it’s important to understand how these actions can affect your income and profitability, making sure they support the long-term success of your practice.

Refinancing debt can directly affect your income by lowering your monthly payments through better terms like lower interest rates or longer repayment periods. This frees up money that can be reinvested back into your business.

On the other hand, debt restructuring involves changing your existing obligations to create a more sustainable financial setup. This might mean combining loans, renegotiating terms, or extending repayment schedules to better manage your finances and reduce the risk of default.

It’s essential to evaluate how these changes might impact your profitability. By reducing interest costs through refinancing and restructuring, you can directly improve your profitability. Having more cash on hand from these strategies allows you to invest in growing your practice, and marketing efforts, and attracting more patients, ultimately leading to increased profitability over time.

Dental practice owners should carefully consider how these changes could affect their income and profits, seeking advice from industry experts and financial advisors to make informed decisions and implement effective financial strategies. By making smart choices and managing finances proactively, dental practices can achieve their full potential for financial success and steady growth.

Important Considerations and Potential Risks

When renegotiating and restructuring debt for dental practices, it’s crucial to carefully consider potential risks and be fully aware of the implications. While these methods can help ease financial burdens and improve cash flow, they require careful planning and understanding.

Understanding how these changes can affect your credit rating is essential. Altering debt arrangements can impact credit scores, affecting your ability to borrow in the future and conduct financial transactions. Consulting with financial advisors or credit experts can help minimize any negative effects.

It’s also important to look at the long-term financial consequences. While restructuring may offer immediate relief, it’s essential to analyze the overall costs, interest rates, and repayment terms of any new agreements.

Variable interest rates come with inherent risks, so it’s crucial to assess your risk tolerance and ability to handle potential fluctuations.

Managing relationships with existing creditors delicately is imperative. Debt restructuring may strain these relationships and be seen as a sign of instability. Open and transparent communication with creditors is essential to maintain understanding.

Compliance with legal and regulatory obligations is a must. This highlights the need for legal and financial expertise to navigate complexities effectively.

In summary, while debt renegotiation and restructuring can be beneficial for dental practices, thorough assessment, expert guidance, and proactive communication are essential for confidently navigating these strategies and fostering sustainable growth.

The Benefits of Refinancing and Restructuring Debt

Refinancing and restructuring debt offer significant opportunities for dental clinics to attain financial stability and success. One major benefit is the potential to secure lower interest rates through refinancing, which reduces monthly payments and overall interest expenses. Extending repayment periods can also ease immediate financial pressures, allowing clinics to invest in necessary upgrades and marketing efforts, ultimately boosting long-term profitability.

Debt restructuring complements refinancing by renegotiating existing agreements for improved repayment terms, such as lower monthly payments or extended durations. Consolidating multiple loans into one simplifies financial management and reduces the risk of missed payments or late fees, providing clarity on debt obligations.

Furthermore, these financial strategies contribute to enhancing the clinic’s credit score, bolstering financial credibility and facilitating access to future credit with favorable terms.

In summary, refinancing and restructuring debt enables dental clinics to enhance their financial well-being, streamline operations, and promote long-term growth and prosperity.
Navigating-debt-financing-4

Steps to Take When Considering Debt Restructuring

Managing debt through restructuring is a critical aspect of financial management that can lead to long-term success. However, it needs thoughtful consideration and strategic planning. Here are steps to navigate debt restructuring effectively:

  1. Evaluate your financial situation comprehensively, including outstanding loans, expenses, income, and cash flow.
  2. Define clear goals for restructuring, whether it’s to lower payments, reduce interest rates, or extend repayment terms.
  3. Explore available options such as debt consolidation, refinancing, or negotiation with creditors, understanding the pros and cons of each.
  4. Seek guidance from financial advisors or debt restructuring experts specialized in dental practices to make informed decisions.
  5. Develop a detailed restructuring plan encompassing financial projections, timelines, and contingency measures.
  6. Maintain open communication with creditors, providing necessary documentation and negotiating terms aligned with your goals.
  7. Implement the restructuring plan diligently, making necessary arrangements and monitoring progress closely.

By following these steps and seeking professional advice, dental practices can effectively manage debt, unlock financial success, and secure a stable future. It’s essential to recognize the power of managing debt to pave the way for improved financial well-being.
Navigating-debt-financing-5

Steps to Consider When Refinancing Equipment and Other Purchases

Consider these steps when financing equipment and other purchases to ensure clarity and potential savings:

  1. Prioritize understanding the varied rates associated with financing options available to you.
  2. Seek detailed explanations of the rates and comprehend the monthly payment obligations.
  3. Explore the possibility of refinancing existing loans, especially if you’re not bound by terms, as low interest rates persist. For newer practices, after 1-2 years, refinancing could yield monthly savings.
  4. Take proactive measures to manage costly short-term debts, such as credit card debt. Consider leveraging equity in your practice or home at potentially lower costs, offering substantial savings in the long run.

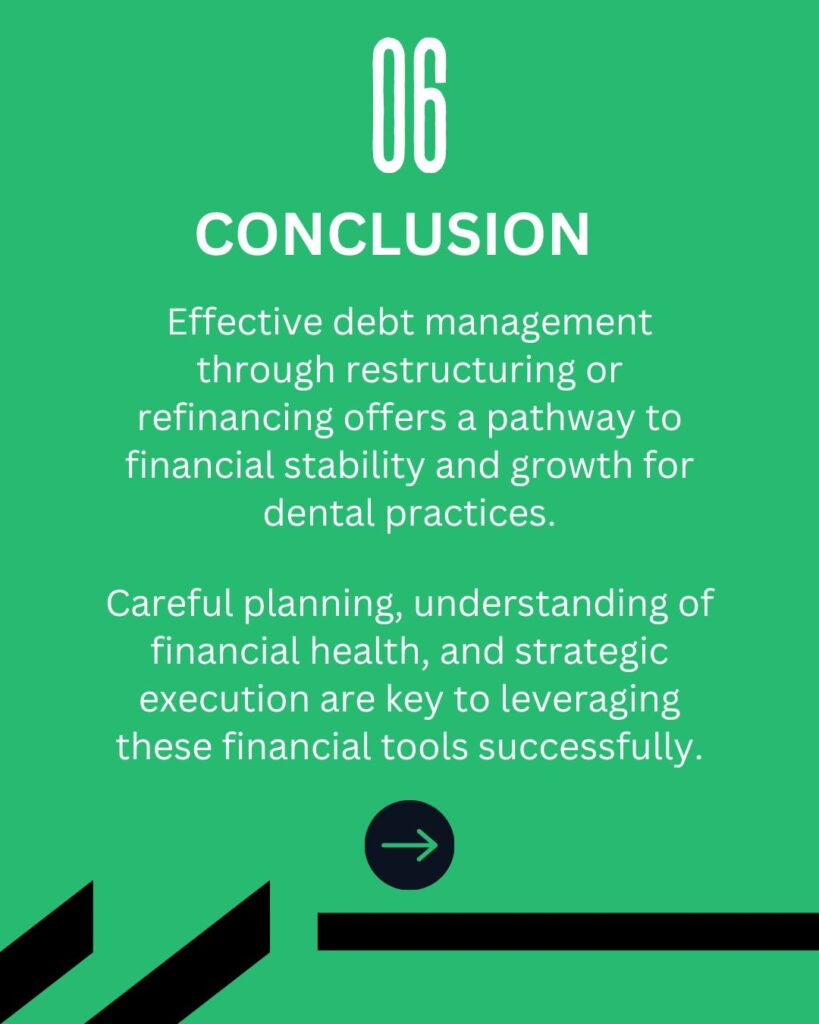
Managing debt can be tough, especially for dental practices, but with the right strategies and knowledge, regaining control of your finances is possible. By exploring refinancing options and restructuring your debt, you can lower interest rates, improve cash flow, and ultimately achieve long-term financial stability. Remember, every dental practice is unique, so consider consulting with financial experts to determine the best approach for your specific situation.

Did You Know?


Dental Practice Operating Costs: Overheads range from 60% to 65% of revenue, mainly due to staff salaries, supplies, and office expenses. [ADA, 2021]

COVID-19 Impact: 76% of dental practices saw reduced patient visits post-pandemic, stressing financial health. [ADA Health Policy Institute, 2020]

Equipment Financing Rates: Interest rates as low as 4% for qualified borrowers, highlighting the need for competitive financing. [Bank of America Practice Solutions, 2023]
Navigating-debt-financing-6

Learn more: Related Articles

Money Saving Tips for Dentists

In this blog, we will discuss ways in which to save money in your dental practice, from utility bills to dental equipment and consumables.

Learn more

Maximising your Dental Practice’s EBITDA

In this webinar, we take you through what you need to know about refinancing and restructuring your debts and finance.

Learn more

Understanding Finance to Increase Profits

In this webinar, we look at how to handle your banks in a cash flow crisis and what you need to be thinking about.

Learn more

Top 10 Tips to Help You Cut Small Business Expenses

This post aims to discuss ten ways to cut small business expenses.

Learn more

About the Author

Neha Jain Author

Neha Jain

Neha Jain is a skilled content writer with a rich background in business and financial knowledge. With a bachelor’s degree in English Literature and Psychology, Neha has honed her writing skills, furthering her expertise with the Content Writing Master Course (CWMC) at IIM SKILLS and a Content Marketing Certification from HubSpot Academy.

Working alongside our business development experts, Neha specialises in helping accountants, dentists and other healthcare professionals start, scale and sell their businesses.

Reviewed By:
Arun Mehra

Arun Mehra

Samera Founder & CEO

Arun, founder and CEO of Samera, is an experienced accountant and dental practice owner. He specialises in accountancy, building businesses, financial directorship, squat practices and practice management.

Follow Arun on LinkedIn

Business Loans for Healthcare Businesses

We’ve been helping to fund the future of British healthcare businesses for over 20 years and our team are made up of former bankers with decades of experience in the UK’s healthcare lending sector.

You can find out more about working with Samera and the financial services we offer by booking a free consultation with one of the Samera team at a time that suits you (including evenings) or by reading more about our financial services at the links below.

For more information on raising finance for your healthcare business, including more articles, videos and webinars check out our Learning Centre here, full of articles and webinars like our How to Guide on Financing a Dental Practice.

Make sure you never miss any of our articles, webinars, videos or events by following us on Facebook, LinkedIn, YouTube and Instagram.
11 Top Tips to Manage your Cash Flow in a Crisis

In times of financial instability, small businesses are usually one of the earliest and hardest hit. There are many issues that can arise from global uncertainty, but amongst the most problematic are disrupted cash flows.

A cash flow crisis can be caused by any number of factors. Disruptions to supply lines, a reluctant customer base or increased expenses.

In the midst of a global emergency such as the Covid-19 crisis, all of these factors can strike at once.

With a cash flow crisis looming for many small businesses, these top tips should help mitigate some of the risks and help manage the cash flow in your business.

Borrow money

One of the simplest ways to manage problems with cash flow in your business is to borrow money to cover the shortfall.

As long as your business has the required credit, you can borrow emergency funds in the form of a short-term loan from a number of different lenders.

You may need to secure your loan with business assets. Consumers are constantly being warned not to panic buy. Similarly, you as a business should not panic borrow!

Always shop around for the best price and seek expert advice when you need it so you get the best deal you can.

Although borrowing money can be a good way of covering unforeseen emergencies, it is not a sustainable fix if you have a prolonged or systemic cash flow problem.

If your cash flow problem is on-going and not caused by sudden, external changes, borrowing money will only delay an inevitable crisis. 

Action Points

During periods of financial instability, small businesses often face cash flow crises due to disruptions in supply chains, hesitant customers, or increased expenses. Amid global emergencies like the COVID-19 crisis, these challenges can intensify. To manage these risks, businesses can consider borrowing money through short-term loans, provided they have the necessary credit. However, while borrowing can address immediate needs, it’s not a long-term solution for sustained cash flow issues. It’s crucial to compare offers, seek expert advice, and explore other strategies to mitigate risks and safeguard business operations.

Apply for a Bounce Back or CBILS Loan

If your business cannot avoid cash flow issues, you may need to obtain a loan to inject some cash into the business.

Although there are several avenues you can try, the UK Government are currently offering 2 loan schemes to struggling businesses – Bounce Back loans and the Coronavirus Business Interruption Loan Scheme (CBILS).

Coronavirus Business Interruption Loan Scheme (CBILS)

The CBILS was launched by the UK Government to provide financial support to small to medium enterprises who have been negatively affected by the Coronavirus and subsequent lockdown.

The scheme is only open to businesses based in the UK with an annual turnover of up to £45 million.

Under the CBILS, businesses can apply for support loans up to a value of £5 million.

However, to be eligible for support your business must prove that it would be financially viable if it were not for the current circumstances regarding COVID-19 and that it has been negatively affected by the virus and lockdown.

You will also need to prove that your business was not classed as a ‘business in difficulty’ on December 31st 2019.

CBILS loans are currently being offered through the normal lending channels.

You can apply by approaching your usual lending platform, such as the high street banks. Over 50 lenders currently participate in the CBILs, and this includes the main retail banks. 

Bounce Back Loans 

The Bounce Back loan scheme was recently introduced by the UK Government following criticism of the CBIL Scheme. Businesses have struggled to obtain funding under this scheme for a number of reasons.

One of the main reasons for this has been the information and documentation required, as well as the financial checks, to obtain the loan. Many businesses are being rejected for funding through the CBILS.

In response, the Bounce Back loan scheme has been launched as a simplified and quicker way for businesses to secure emergency funding. 

Through the Bounce Back Loan Scheme, businesses can apply for funding between £2,000 and £50,000.

The UK Government will guarantee 100% of the loan and you will not be required to pay any interest, or make any repayments during the first 12 months. Loan terms will be offered at up to 6 years. 

Small to medium enterprises who are based in the UK and have been negatively affected by the pandemic are eligible to apply. 

Like the CBILS, the Bounce Bank Loans Scheme is being offered through the regular financial lending channels, such as the major retail banks. 

Action Points

If your business is facing cash flow issues, consider applying for a loan through the UK Government’s schemes – Bounce Back loans and the Coronavirus Business Interruption Loan Scheme (CBILS). CBILS offers support loans of up to £5 million to UK-based businesses with turnovers up to £45 million, provided they demonstrate viability without COVID-19 impacts. Meanwhile, Bounce Back Loans offer simplified, faster funding between £2,000 and £50,000, with the government guaranteeing 100% of the loan and a 12-month interest-free period. Both schemes are accessible through regular lending channels, including major retail banks, and aim to provide relief to small to medium enterprises affected by the pandemic.

Contact us to find out more

Seek investment capital 

Similarly to borrowing money, you can seek investors who are willing to buy equity in your business.

Although this differs from borrowing money in that your business does not take on debt, it does mean that you will be giving up some level of control or ownership of your business – depending on how much capital you raise.

It is important to remember that you are in effect taking on a business partner. It is essential that you find the right partner to invest in your business!

Do not rush into any agreements, do your research on your potential partner and understand that this partnership may be permanent. 

Action Plan

Consider seeking investment capital as an alternative to borrowing money, where investors purchase equity in your business. While this avoids accruing debt, it involves relinquishing some control or ownership. Choose investors carefully, as they become long-term partners in your business. Conduct thorough research and ensure alignment of values and goals before committing to any partnership agreements, as they may be permanent.

Get paid quicker

Solving a cash flow crisis does not necessarily mean getting more money into the business.

You can also alleviate cash flow problems just by streamlining the flow of money within the business.

By making processes smoother and more efficient, you can more effectively move money through the business and ensure you have a steady cash flow.

One way to do this is to speed up how money flows into the business.

If you do not already have some form of online payments set up for your customers, you need to provide this functionality as soon as possible.

Not only do most consumers expect online payment as standard nowadays, instead payment can ensure you are not waiting on customers or banks for money you have earned. 

You can also start requesting deposits for payments. If you already request deposits, you may also think about increasing the amount.

Charging deposits means you get some instead, ready cash into the business for a product or service – even if it is not the full amount! 

Another way to speed up payments is to send your invoices earlier and more frequently than you would otherwise do.

Sending invoices immediately after services rendered decreases the amount of time you spend waiting on payment.

You can also negotiate to send incremental invoices over a period of time, rather than a final invoice upon completion of the service or product.

This will allow you to keep up a smaller, steady stream of funds within the business. 

Action Points

To improve cash flow, streamline processes for faster money movement. Offer online payments, request or increase deposits, and send invoices promptly. Negotiate incremental invoicing to maintain a steady cash flow. These strategies ensure a consistent flow of funds and mitigate cash flow challenges.

Pay money slower

Another way to improve your cash flow is to delay money leaving the business.

If you have regular expenses then you may need to think about renegotiating the payment structures you currently have in place.

If, at the moment, you pay for a particular service monthly, you may be able to revise this to a quarterly payment structure.

This can help buy time by letting you keep much needed money within the business until absolutely necessary. Do not pay bills and invoices until they are due.

Paying early may earn you goodwill (and you can use this to negotiate a better payment schedule), but it will not help you in a cash flow crisis. 

Contact your utilities providers (such as electricity and internet) and see if you can negotiate a better deal. Remember, most businesses want your business.

If you let them know you are thinking of moving to a competitor, they will usually try to get you a better deal to keep your custom. Try it out! 

Action Point

Delaying outgoing payments can help preserve cash flow. Renegotiate payment schedules to pay expenses less frequently, such as switching from monthly to quarterly payments. Avoid paying bills before they’re due, as this drains cash unnecessarily. Negotiate better deals with utility providers by leveraging competition. Holding onto funds longer ensures greater financial flexibility during cash flow challenges.

Ask for a payment holiday

Another way to reduce your monthly outgoings is to ask for a payment holiday from your lenders. This can include any financial institution to whom you currently owe monthly payments, such as your banks.

Some banks are currently offering 3 month holidays on certain loan terms, others are even offering 6 months! 

Of course, whether or not you can agree to a payment holiday will depend on your bank and your loan term.

However, many banks and financial lenders are being fairly generous and understanding at the moment so it is certainly worth trying! 

You can also try asking for a payment holiday from your landlord. Again, whether or not you can get your landlord to agree to a deferred payment will depend on your landlord and your ability to negotiate.

Like the banks, some landlords are being generous at the moment so it is worth contacting them and seeing if a deal can be reached. 

For instance, you may offer to pay monthly instead of quarterly to ease cash flow. Alternatively, you may ask to pay smaller amounts each month and agree to make up the balance when lockdown ends. 

It may be a long shot for some, but it is worth everyone trying!

Action Plan

Requesting payment holidays from lenders and landlords can ease financial burdens during tough times. Many banks offer three to six-month breaks on loan repayments while negotiating with landlords for deferred rent payments or adjusted schedules is also helpful. Proposing alternative payment arrangements, like monthly rent installments or partial payments with future settlement plans, may be advantageous. Though results vary, exploring these options can provide much-needed financial relief.

Explore alternative supply chains

Whilst you are trying to renegotiate prices with your suppliers for a better deal, you may also want to think about exploring different supply routes.

To take the Covid-19 crisis as an example; if some of your supplies come from China, you may want to think about finding an alternative source.

Not only do socio-political crises have huge impacts on trade and supply, consumers may also be put off by the idea of their goods coming from an affected region.

Try to make sure your products and resources are brought in via safe, stable and affordable supply chains. 

Increase prices

Another obvious way to improve cash flow is to increase the cash. One of the easiest ways to do this is to increase your prices for goods and services.

Naturally, a lot of small businesses are wary of increasing prices for fear of driving away customers.

This is especially true of newer businesses. If you have a reliable and returning customer base, you may be surprised at how many are willing to accept a price increase.

If your customers appreciate your business and what it offers, they will be willing to pay a little bit extra.

You can also make a big deal about lowering your prices again once the problem has subsided!  You could also offer a VIP or Gold Service option for your services or products.

By offering a little bit of exclusivity to your services, a small percentage of consumers will be willing to pay a large price for the VIP treatment. 

Make sure you do your research into your competitors. Do not price yourself out of the market and keep your business competitive. 

Action Point

Exploring alternative supply chains can mitigate risks during crises like Covid-19, ensuring stable access to resources. Increasing prices, albeit cautiously, can boost cash flow, with loyal customers often accepting moderate hikes. Offering premium services at higher rates and promoting eventual price reductions post-crisis can attract select clientele. However, competitive pricing adjustments are essential to maintain market competitiveness.

Cut expenses

A quick, easy win for solving cash flow problems is to cut unnecessary expenses. It is essential that you regularly review your business expenses even in times of calm.

In times of crisis, it is doubly important. There is no business out there that does not have unnecessary expenses. If you can find them and cut them, you can save yourself a lot of money.

Conduct a review of every single penny your business spends. Ask yourself; do I need to spend this money, or do I need to spend this much money?

Cutting expenses doesn’t have to mean ceasing entire initiatives. Saving a small percent in several areas can result in a huge savings.

Cutting down on lighting and heating when not being used, decreasing office supply wastage, limited employee expenses – a small reduction in several key areas can free up vital cash.

Try replacing costly measures with cheaper alternatives For instance, video meetings work just as well as face-to-face meetings without all the added costs like travel and refreshments. 

Action Point

Trimming unnecessary expenses is vital during financial challenges. Regularly evaluate all expenditures, identifying and eliminating non-essential costs. Even small reductions across multiple areas can accumulate into substantial savings. Consider cost-effective alternatives, like video meetings instead of in-person gatherings, to further curtail expenses while maintaining productivity. Prioritizing efficient resource allocation is essential for safeguarding cash flow and bolstering financial resilience.

Sell non-essential assets and reduce inventory

Most businesses own assets and most assets are necessary for the day-to-day running of the business. However, there will almost certainly be assets in your business that are non-essential and can raise much-needed funds. 

Take a full inventory stock of your business. Include everything the company owns and sort everything into essential and non-essential items.

Take a look at your non-essential list. Some of these assets you will be able to do without completely. In these cases, your best bet is to simply sell them.

You may end up selling for less than you bought the item. Although you want to try and get the best price you can, your goal is to free up cash, not turn a profit. 

If your business involves selling large quantities of items, you may need to think about reducing your inventory.

Make sure you factor this into your stock flow management to ensure you do not face a shortage of essential materials and goods. Try and keep as small of an inventory as possible to ensure your cash is not tied up, immobile in your stock. 

Action Point

Consider selling non-essential assets to generate much-needed funds during financial challenges. Conduct a thorough inventory of your business assets and distinguish between essential and non-essential items. Items deemed non-essential can be sold to free up cash, even if it means accepting a lower price than their original purchase value. Additionally, evaluate your inventory levels and consider reducing them to prevent excess cash from being tied up in stock. Maintaining a lean inventory ensures liquidity and agility in managing your business finances.

Contact us to find out more

Do a Cash Flow Statement 

The best way to manage your money is to keep track of it and know exactly where it is at all times.

It is essential that you know exactly how much money is being brought into the business each month and, more importantly, where it is all going. 

The most efficient way to do this is to create a cash flow statement. By listing out every expense your business has, you will find it far easier to manage your money. 

Cash flow statements allow you to better identify where the majority of your money is going and the best areas of the business to make savings.

You may find that you are spending more than you thought in areas of the business you hadn’t considered, or in areas that could afford to be underfunded for a few months. 

Cash flow statements allow you to plan your budget, identify when you may need additional capital in the business and keep track of exactly how much money the business has.

By properly using a cash flow statement, you will be able to keep cash flow shortages to a minimum.

Action Plan

Craft a cash flow statement to monitor your business finances closely. This tool helps track cash inflows and outflows, providing valuable insights into spending patterns. By detailing expenses, you can identify areas to cut costs and prioritize expenditures. Use the statement to plan budgets, forecast capital needs, and maintain financial clarity. With diligent oversight, you can mitigate cash flow gaps and optimize resource management.

Download our cash flow statement template for free below:

How to use the cash flow template

By clicking the link below, you can download our template for a cash flow statement. With a few adjustments, this template can be adapted to be used by almost any business.

The template is currently filled in with example information to illustrate what a finished forecast may look like. Please feel free to delete these numbers and replace them with your business’s own figures.

To calculate your business’s incoming cash, please fill in the ‘CASH INFLOWS’ section with your gross turnover (including VAT), your standing debtors and the value of any furlough receipts you may have received from HMRC. Cells labelled ‘other’ have been left blank for you to include any other revenue streams.

To calculate your business’s outgoing cash, please fill in the ‘CASH OUTFLOWS’ section with your standing creditors and the various expenses currently listed. Again, cells labelled ‘other’ have been included for you to add any additional expenses you may have.

The forecast spreadsheet will then show you the net movement of your business’s in-comings and outgoings. By also entering in your starting bank balance, the forecast then shows your business’s cash balance at the end of each month for the next year.

Action Point

  • Download the template.
  • Replace example numbers with your business’s figures.
  • Enter cash inflows and outflows.
  • Review net movement.
  • Input starting bank balance.
  • Determine cash balance for each month.

Managing Cash Flow: Conclusion

As the effects of the Coronavirus crisis are felt throughout the world’s economy, businesses across the globe will feel the pinch. Cash flow will become problematic for all manner and size of business, so it is essential to be prepared.

Making small savings in several areas can result in a huge saving across the business.

Additionally, planning your cash flow with a cash flow template can help you identify and avoid problems before they happen.

If you are experiencing unavoidable cash flow issues, you may benefit from applying for one of the Government-backed support schemes.

Using these tips, you can try to save as much money as possible while ensuring the smooth operation of your company. 

Check out our other articles, webinars and podcasts in the Samera Learning Centre

Learn more: Related Articles

Financial Tactics During a Cash Flow Crisis

In this webinar, filmed during the first lockdown, Arun discusses vital financial tactics that you need to be taking to manage your cash flow in a crisis.

Learn more

Managing Your Cash Flow in a Crisis

In this webinar, filmed during the first lockdown, Arun discusses tough decisions every business needs to make in a crisis to manage their cash flow.

Learn more

How Should a Dental Practice Organise its Finances

In this article, we will talk about some tips and methods to help you organize and handle your finances better. We’ll cover everything from creating a budget and tracking expenses to looking at financial reports and managing your income. 

Learn more

Creating a Business Plan for a Dental Practice

This is how to create a business plan for a dental practice. Download a free business plan template here too.

Learn more

About the Author

Arun Mehra

Arun Mehra

With almost twenty years of commercial experience and knowledge in Dentistry, Arun’s expertise is valued by hundreds of businesses across the UK. His financial acumen and know-how, along with his hands-on commercial expertise have helped clients, large and small, new and established to achieve great things.

Arun is the founder of the Samera Group, starting the business with just one client sitting at his father’s dining table. Fifteen years on, Team Samera now service hundreds of Dental clients, run exciting events, help clients raise finance, and are very active in helping clients buy or sell Dental practices.

Join the Samera Alliance Buying Group

The Samera Alliance is our growing network of dentists, practices and leading industry suppliers, designed to help you save money, grow your profits and build a better dental business.

Join today for free to be a part of our dental buying group, which gives you access to exclusive discounts and offers on the consumables, equipment and products you need to run a successful dental business.

You’ll also get better rates and terms for a wide range of services like HR, IT, utilities, insurance, legal services and much more!

Business Loans for Dentists

We’ve been helping to fund the future of the UK’s dentists for 20 years and our team are made up of former bankers with decades of experience and contacts in the UK’s healthcare lending sector.

You can find out more about working with Samera Finance and the financial services we offer by booking a free consultation with one of the Samera team at a time that suits you (including evenings) or by reading more about our financial services at the links below.

Dental Practice Finance: Further Information

For more information on raising finance for your dental practice, including more articles, videos and webinars check out our Learning Centre here, full of articles an webinars like our How to Guide on Financing a Dental Practice.

Make sure you never miss any of our articles, webinars, videos or events by following us on Facebook, LinkedIn, YouTube and Instagram.
Top 10 Tips to Help You Cut Small Business Expenses

Running a business costs money. Even with less expensive technology and marketing tools, somehow costs still manage to add up and unfortunately, these costs can continue to increase regularly. To help keep your profits up, you need to be able control your expenditures effectively and cut a few corners to help you save that extra pound here and there to decrease your overall expenditure. Here are ten ways to cut small business expenses.

Start saving

Remember when our parents used to tell us to make sure we are saving at least half of our allowance, it is the same for business! It can be hard to think about putting money away while you have consistent cash flowing in and out.

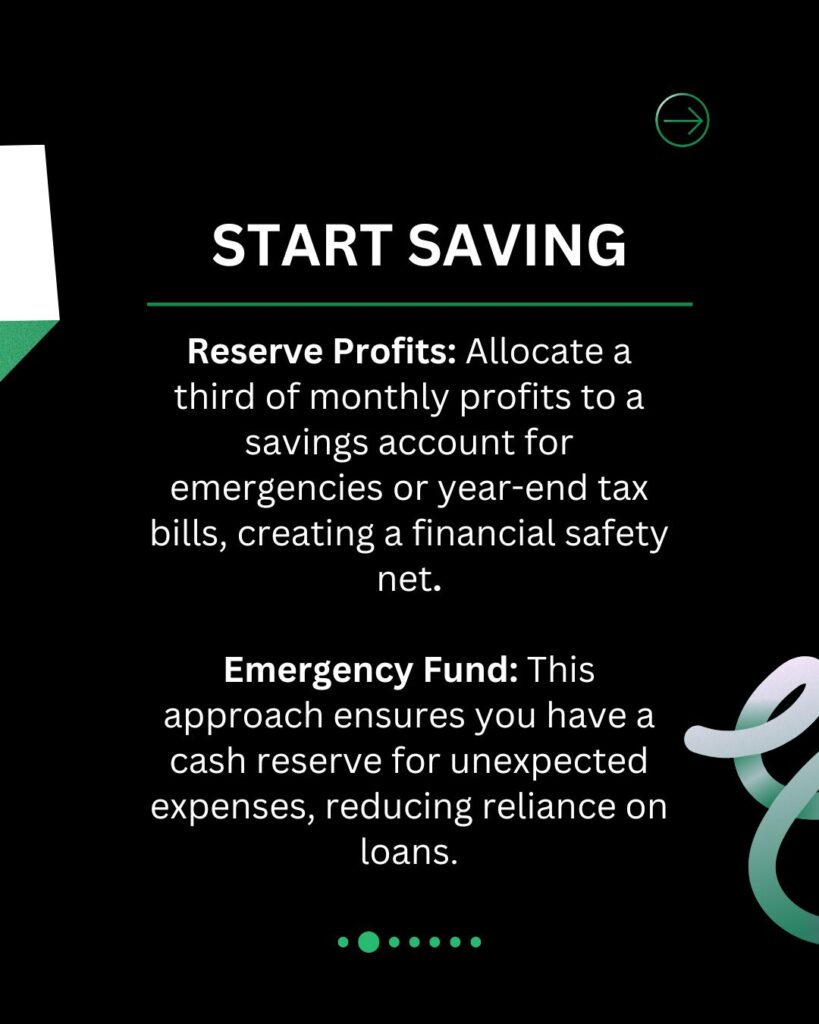
But a good tip to try to save some money is to reserve a third of profits every month into a hard to reach bank account. This can then be used for an end of year tax bill for your dental practice or in the event you need cash for an emergency. This savings account can be your saviour when you have unexpected expenses, it will act as a surplus of cash sitting there without you having to rely on a loan.

Action Point

Saving money is essential for businesses, just like it is for individuals. While it may seem challenging to set aside funds when cash flow is consistent, it’s crucial for financial stability. A helpful strategy is to allocate a portion of profits, such as a third, into a separate savings account each month. This reserve can serve as a buffer for unexpected expenses or end-of-year tax obligations. By building up savings, your dental practice can avoid reliance on loans and have a safety net for emergencies.

Top-10-tips-to-cut-small-expenses-1

Get points

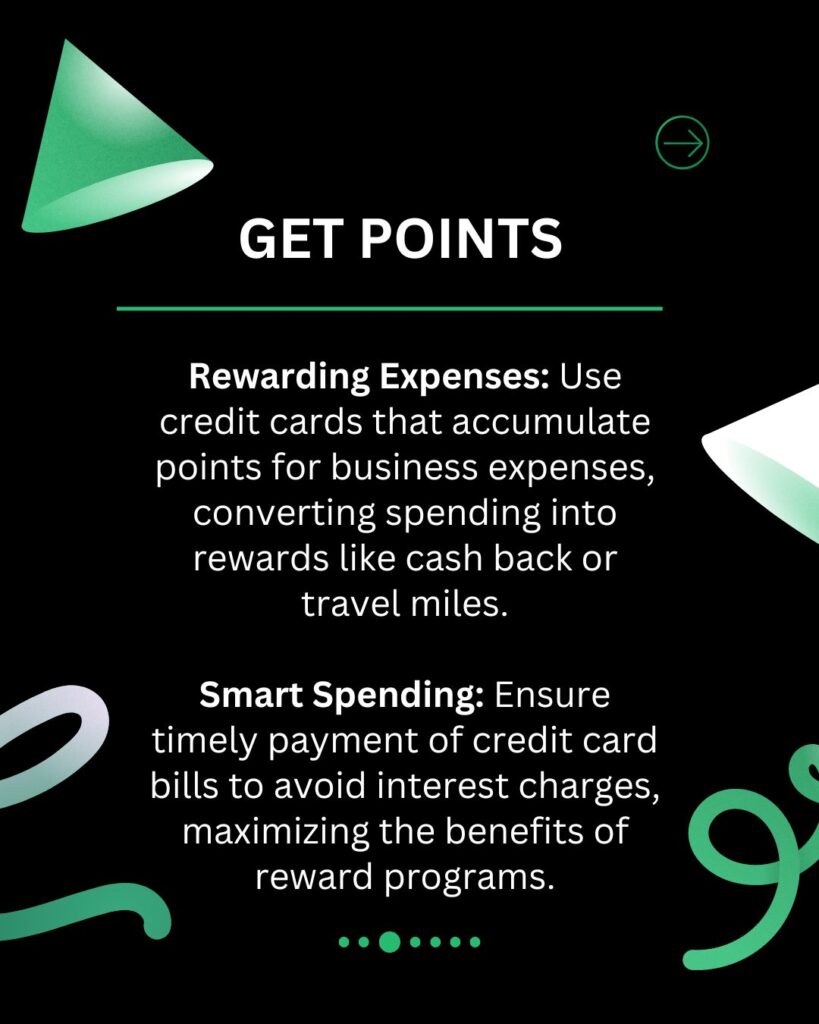
When making big expenses, try to pay as much as you can on a point accumulating credit card. Cards such as American Express or British Airways Miles give you rewards when you spend with them. American Express points transfer into money while continuous spending with a BA card can convert points into miles and allow you to save on business trips.

Remember to be sure to pay your monthly bill so you don’t end up racking up any extra charges. No matter what sector your company is in, every business, including dental practices, has expenses. So, you might as well be earning while you are spending. 

Action Point

Maximize rewards by using point-accumulating credit cards for significant expenses, like American Express or British Airways Miles, but ensure timely bill payments to avoid extra charges, benefiting dental practices and other businesses alike.

Top-10-tips-to-cut-small-expenses-2

Minimising Taxes

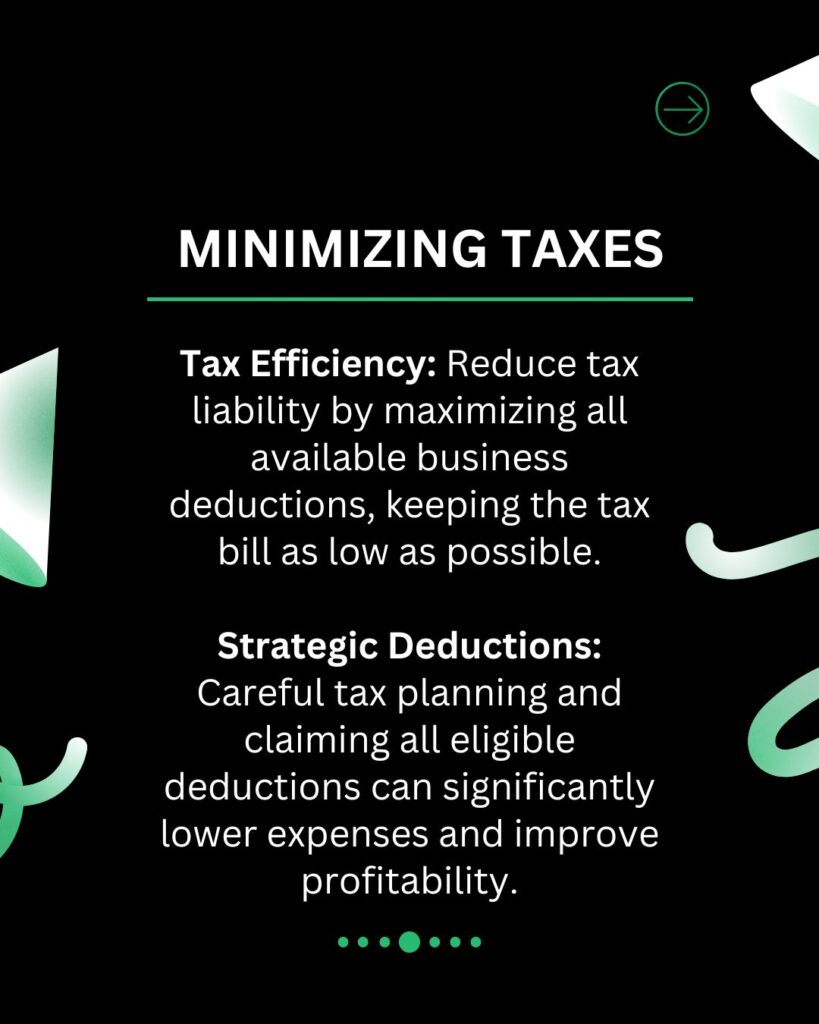
Keeping the taxman at bay is one of the most important tips we could ever give you. Minimising your tax bill can be the most beneficial way to improve your business expenses. Taxes are the one expense that cannot be avoided, but minimising them is a great way of working around this issue. This means maximising all your available business deductions in order to reduce your tax liability. 

Action Point

Maximize available business deductions to reduce tax liability, effectively minimizing expenses and improving overall financial health for your dental practice.

op-10-tips-to-cut-small-expenses-3

Keeping track 

The best advice we can give you is that when you stay on top of all your expenses and payments, you have control over your cash flow which is the best position you can be in. Even if you are slightly lacking in profits, the control you have over your outgoings will help you get on a path that will allow figures to get higher. 

You should also get into a habit of keeping track of all business expenses, that means every single one including keeping receipts. An expense that is often overlooked is vehicle mileage. If you are serious about cutting your expenses then you need to record the mileage you do for business purposes. 

Action Point

Maintaining meticulous records of expenses and payments empowers you to control cash flow, paving the way for improved profitability, while diligently tracking every business expense, including often overlooked items like vehicle mileage, is crucial for effective cost management.

Top-10-tips-to-cut-small-expenses-4

You can download a free cash flow forecast tool here.

Make the most of your time

It is important to know the value of your time and to make sure you are using it efficiently. Many business owners swap time in an effort to save money. An example of this is when you are driving an hour to pick up supplies and stock to save on a £10 shipping cost.

By doing small things like this you are essentially saying your time is worth less than £10 an hour! Not to mention the fuel costs included. The hour you wasted driving could have been utilised in a better way for you to earn more money than the money you didn’t save, but lost in that hour. Efficiency leads to more productivity and profit. And it all starts with knowing your goals, being organised and having a plan. 

Many successful entrepreneurs begin their day with a morning routine that sets the day for productivity. Having a schedule and routine will help you time manage your life to keep you productive and efficient.

Finally, delegating and outsourcing. The weight of your entire business should not rest on your shoulders. There are ways to delegate and outsource certain jobs that do not have to be done by you. In order to improve efficiency, outsource certain business practices to a third party specialist.

It might seem like hiring an outside vendor will increase your costs, however, in the long run, delegating specific tasks to specialists can save you money and generate even better results by leaving you time to do what you do best. There are also cost effective ways to do this such as using apps and websites such as upwork or automation tools that can help you take care of your business needs while you have the time to focus on what you do best in your business.

Top-10-tips-to-cut-small-expenses-5

Contact us to find out more

Switch to the cloud

For many businesses a great way to reduce capital costs and ongoing IT related expenses is to switch to cloud computing. Cloud computing will help your business thrive by optimising costs and improving efficiency. With cloud computing, the need to purchase and maintain expensive ongoing software updates and servers on site is diminished.

The cloud allows you to always have the latest versions of business applications and your cloud provider will be able to take care of most data recovering issues, hence freeing your business from worrying about the implications and expenses of complex IT disasters. 

Action Point

Transitioning to cloud computing not only reduces capital costs and ongoing IT expenses but also enhances efficiency by providing access to the latest software versions without the need for expensive on-site servers, while cloud providers handle data recovery, alleviating concerns and expenses associated with IT disasters.

Top-10-tips-to-cut-small-expenses-6

Avoid interest charges

This is one of the most important tips we can give you. Before embracing small business financing options for your dental practice, or any sort of credit, you need to calculate the interest rates that you are going to accumulate. Every pound that you pay in interest is a pound that will not accrue to your net earnings. Before venturing to find any kind of capital that will incur high interest, try tapping into friends and family favours for interest-free start up capital! 

A great tip is to pay off your highest loan rate first. So any short term rate, high debt that you may have such as credit cards or short term loans, always pay this off before you land yourself in hot water. Otherwise, you will be accumulating higher and higher costs and interests which will result in you eventually paying out more than what is coming in. Staying on top of these costs will allow you to keep on top of profits and manage costs effectively. 

Action Plan

To maintain profitability and manage costs effectively, it’s crucial to avoid interest charges by prioritizing the repayment of high-interest debts, such as credit cards or short-term loans, and seeking interest-free startup capital from friends and family before resorting to small business financing options, as every pound paid in interest detracts from net earnings.

Top-10-tips-to-cut-small-expenses-7

Raise fees

Raise your fees routinely. A 10% increase in fees can lead to a much larger increase in profits if your overheads are remaining constant. So always look at your prices on a very regular basis as this can make a huge impact on the profitability of your business.

Consider setting up a premium or VIP service in your business. A small percentage of your customers will be willing to spend a lot on a premium or exclusive service. Even a handful of customers paying for VIP products or services can result in a large profit.

Action Plan

Regularly reviewing and raising your fees, even by a modest percentage, can significantly boost profitability, especially if overhead costs remain stable, while offering premium or VIP services to a select clientele can generate substantial profits from a small customer base.

Top-10-tips-to-cut-small-expenses-8

Pay invoices early

There are many vendors that offer small discounts to clients that pay invoices ahead of schedule. It is these discounts that add up at the end of each month showing you how much you can save. As long as paying early does not impact your cash flow negatively, it usually makes financial sense to do so and also gain personal credit with the vendors knowing that you are a standup customer. 

It is also very important to remember to always get free quotes for any big capital item you purchase as prices vary greatly amongst distributors. And you should do the same for small supplies that you do every month such as materials. Price Match products at least once annually. You will be surprised how much you will be able to save from comparing costs. 

Action Plan

Paying invoices early can lead to significant savings through vendor discounts, while obtaining free quotes for capital items and price matching small supplies can further reduce costs and improve financial efficiency.

Top-10-tips-to-cut-small-expenses-9

Click here to read our article on Dentist and Dental Associate Expenses Guide

Cut costs

When you shop around to find deals you will be surprised at the difference in rates for the same products from different suppliers and providers. As a small business owner you are always looking for ways to optimise your resources and cut material costs, here are a few suggestions on how to cut small business expenses:

When it comes to wholesale supply costs, every penny saved is essentially a penny earned. If you are running a business that regularly makes a lot of wholesale supply purchases, getting the best deal on supplies can make a huge difference with your outgoings. As a business owner you need to be constantly monitoring supply costs and checking for discounts as well as alternative lenders with better prices.  

You can also cut advertising costs as there are now more potential customers online now than ever before. Advertising does not have to be expensive, you can start by simply creating an online presence through social media or a website. Direct email is another highly effective low-cost marketing solution. Publicity is free and a great low-cost way to build your credibility. Other great cost effective options include cold calling, carrying business cards and asking for referrals. 

Insurance is an expense that no business can evade, you cannot afford to avoid spending money on insurance. However, increasing your deductible is one way to reduce your premiums. Just be sure that the amount of your deductible is not higher than what your business can afford if you have to make a claim. If you are a member of a professional organisation or a big company, you may be able to take advantage of group rates. 

Action Point

Cutting costs through strategic monitoring of supply expenses, leveraging discounts, and exploring alternative suppliers, alongside adopting low-cost marketing methods and adjusting insurance deductibles, can significantly improve a small business’s financial health.

Top-10-tips-to-cut-small-expenses-10

More on how to cut small business expenses

In conclusion, within every business in our uncertain economy, every penny counts, even the smallest percentage off an entire invoice will save you money. The biggest aspect of managing your spending is managing your time.

As your business grows, understanding things like operating costs and cutting any unnecessary costs is going to become more and more important. Operating costs will allow you to take an in-depth look at how your expenses are impacting your profits. Once you start cutting unnecessary costs you can start boosting profits.  

Top-10-tips-to-cut-small-expenses-11

You can find more tips on how to manage your cash flow here.

About the Author

Arun Mehra

Arun Mehra

With almost twenty years of commercial experience and knowledge in Dentistry, Arun’s expertise is valued by hundreds of businesses across the UK. His financial acumen and know-how, along with his hands-on commercial expertise have helped clients, large and small, new and established to achieve great things.

Arun is the founder of the Samera Group, starting the business with just one client sitting at his father’s dining table. Fifteen years on, Team Samera now service hundreds of Dental clients, run exciting events, help clients raise finance, and are very active in helping clients buy or sell Dental practices.

Need help with your dental accounts?

Samera works with dental associates, practice owners and dental groups to manage accounts, tax, bookkeeping and financial reporting. If you want clearer numbers, less admin and a system that works throughout the year, book a free consultation with our dental accounting team.

Contact us to talk directly or find out more about our accountancy services:

Financial Tips for Dentists

Arun’s 11 Financial Tips for Dentists that can lead to Financial Freedom

It shocks and saddens me when I see many young, energetic dentists excited about their careers but really managing their hard earned cash through poor advice.

It’s well known upon University graduation, Dentists are amongst the highest earners, but I have seen with my own personal eyes the poor judgement that many dentists use in managing their money.

A flash car, or a new fancy handbags may give short term satisfaction, but within a week or two, many wonder why they have bought the item in the first place and quite possibly regret trying to keep up with the Jones’.

My name is Arun Mehra, and for almost 20 years my accountancy firm has been working with Dentists. I married a Dentist, Smita Mehra (owner of the The Neem Tree Dental Group) back in 2001 and since then I have helped 1000’s of dentists across the globe with their business and finances.

I have been around the block a few times, and just like you, I do like to enjoy what life has to offer, but never at the cost of keeping up with the Jones’s. In this blog post I have put together some financial tips for dentists.

Financial Freedom for Dentists

The key to serious financial freedom is investing in opportunities that build you a passive income, and not wasting money on pointless things that have no real impact on your life. Earning money is hard work, so why waste it so frivolously?

This blog post is all about what you should be, and shouldn’t be doing in terms of your money. So, here are my top financial tips for dentists.

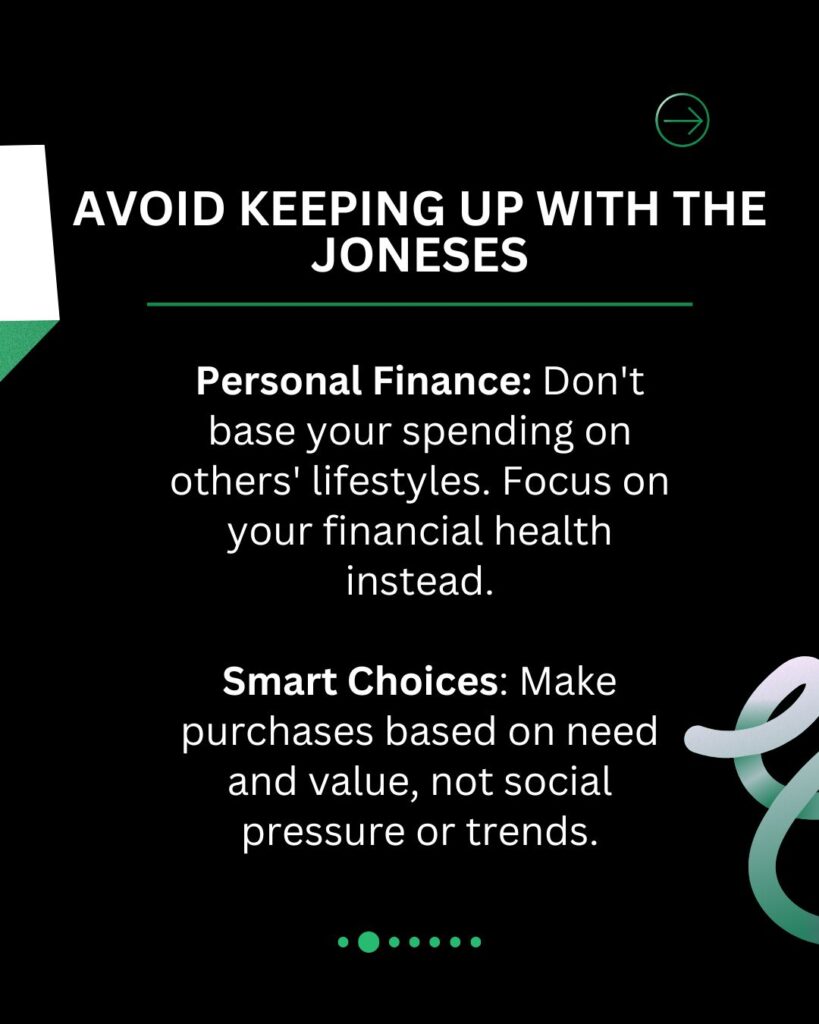
Rule 1 – Never try and keep up with the Joneses.

Who cares if your colleagues or friends have the latest car or newest piece of tech, don’t judge your situation on what they have or are buying. Look at your own finances, and then make the judgement of, can you afford it? And if you can, what will it bring to you?

Financial-tips-for-dentist-1

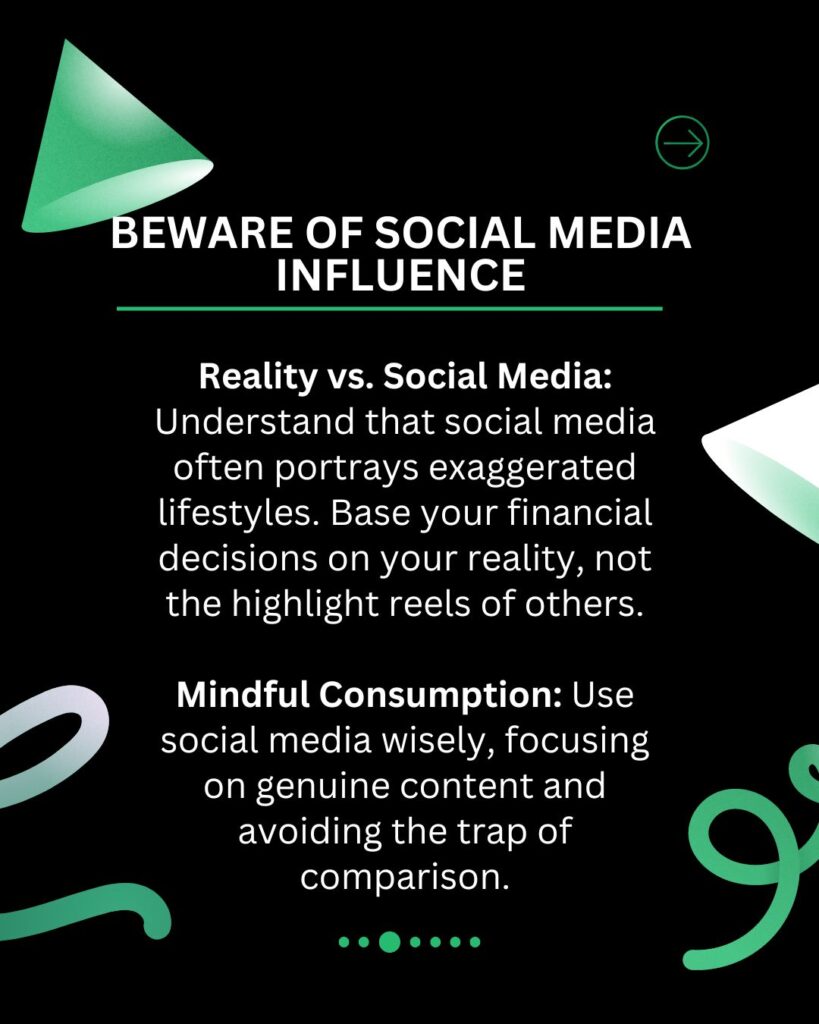
Rule 2 – The curse of Instagram.

If we all believed what we saw on Instagram, it would appear that everyone is a billionaire, living the high life everyday.

They are not, it’s simply them trying to show off to others that they have made it. Some may have, but most haven’t.

Ignore what you see people buying on Instagram, or better still turn it off. If you do want to use it, don’t believe the hype, do your own research and take everything you read or see with a pinch of salt!

Financial-tips-for-dentist-2

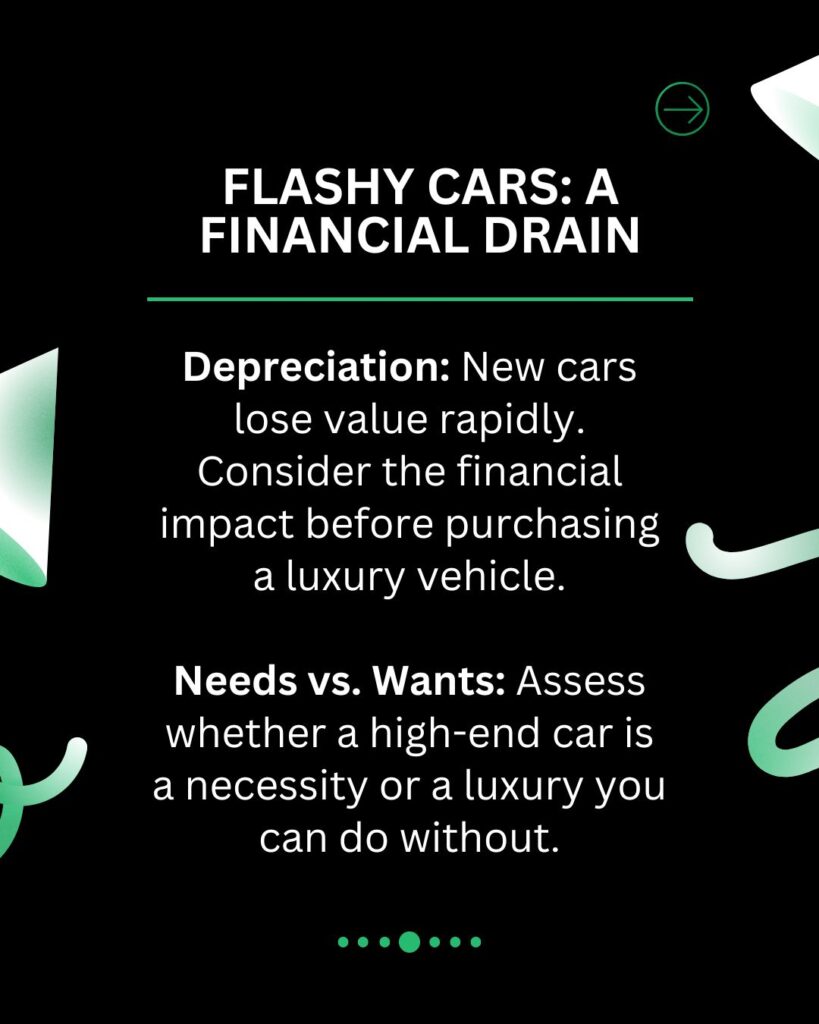
Rule 3 – Flash cars

There are various forums across Social media that show the latest flash car that your mate or colleague is buying.

Don’t be tempted unless you are a serious car dealer as buying the latest flash car is tantamount to financial nonsense.

Yes, the cars look lovely and shiny, but its not a financial investment and once you have driven it out of the fancy showroom it will lose at least 20% from what you paid for it.

I appreciate you may need a car, but does it need to be over £75,000 with all the trimmings? Probably not.

Financial-tips-for-dentist-3

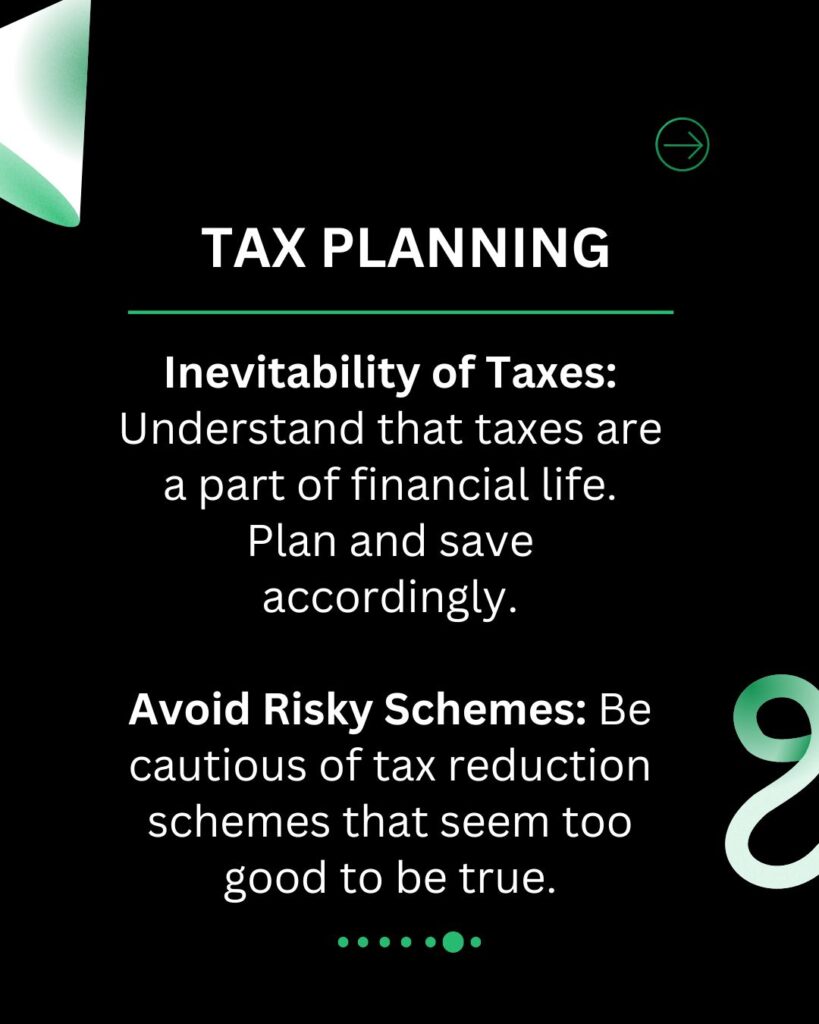
Rule 4 – Tax is inevitable

Don’t believe the hype that you can drastically reduce or eliminate your tax bill. My firm has picked up the remnants of many a dentist who has been easily persuaded to invest in various schemes over the years to reduce their taxes.

In truth, most never work, and be careful who actually advises on such schemes. Tax schemes very rarely work and often come back to bite – with a vengeance.

Financial-tips-for-dentist-4

Contact us to find out more

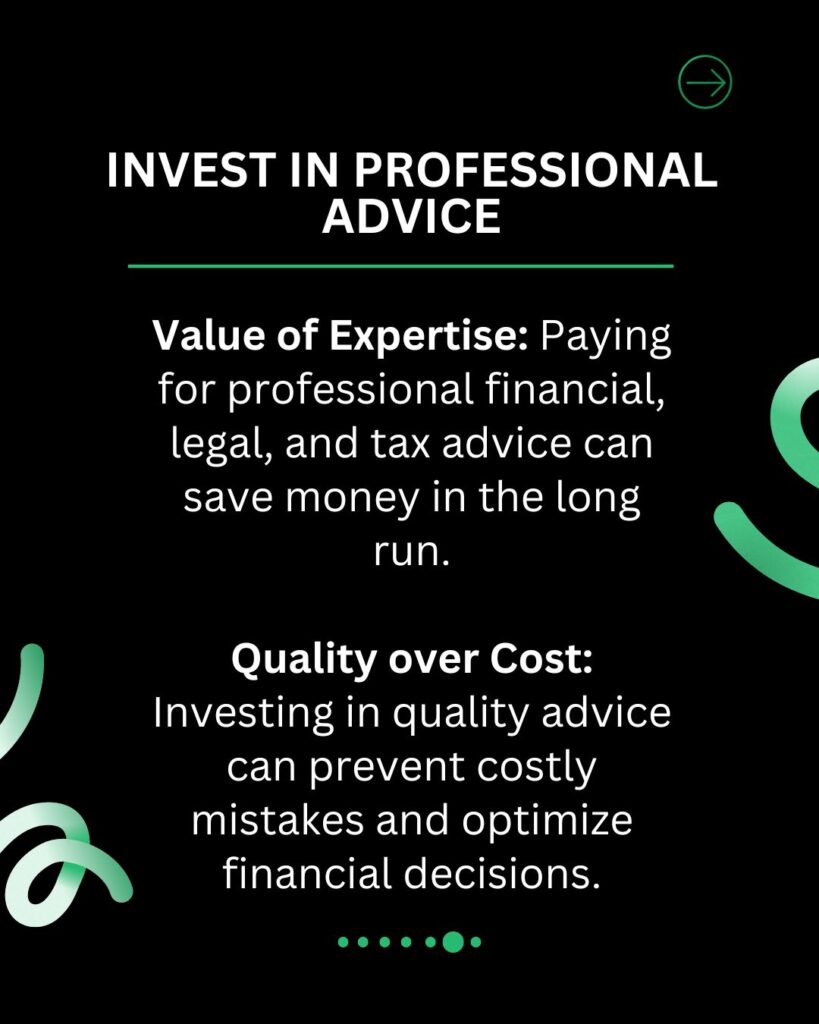
Rule 5 – Pay for proper professional advice

You may find this difficult, but pay for the best advice possible from the right professionals – if you pay, you will get the right advice on most occasions.

I happily pay lawyers, tax advisors, surveyors and others when I need them, so I get the best result for whatever I am trying to do. If you need some support from our professional dental accountants click here.

If you don’t pay, and try and take shortcuts, it usually comes back to bite.

Financial-tips-for-dentist-5

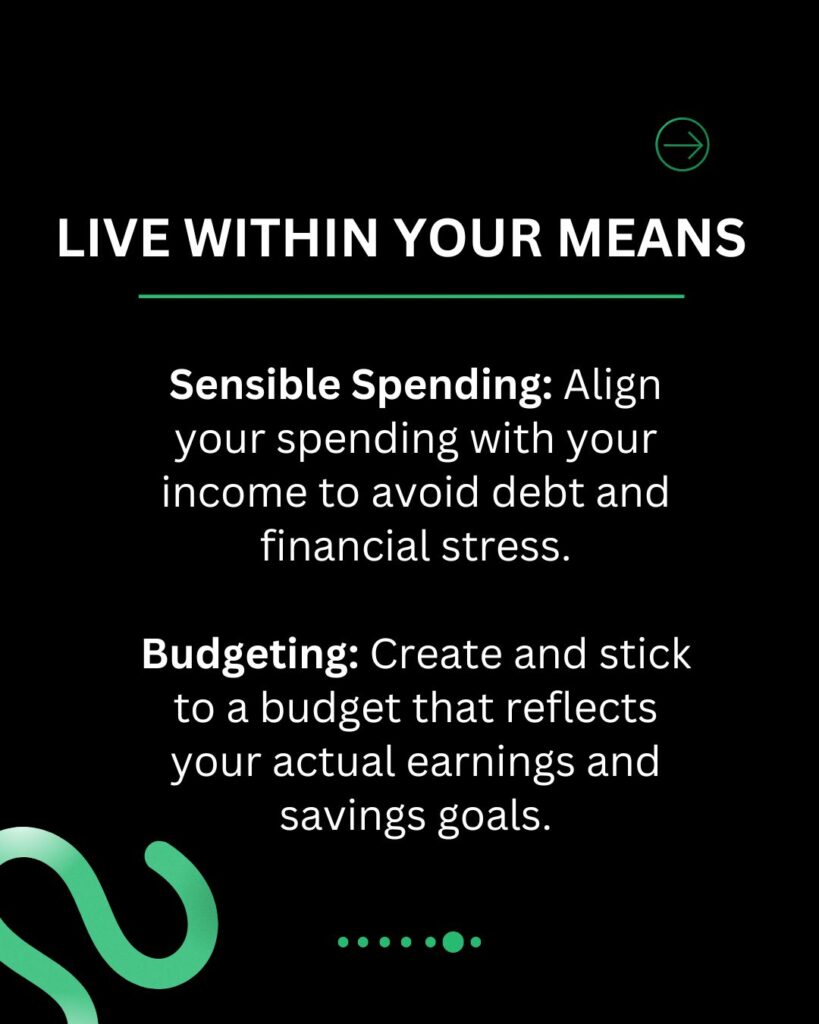
Rule 6 – Cut your coat according to your cloth

Yes this old Chinese proverb still stands today, with the free availability of credit to all.

Don’t get sucked in (see rules 1 and 2 above) and apply a degree of sense when spending your hard earned money.

Financial-tips-for-dentist-6

Rule 7 – Save every month

Yes I know it’s boring, and interest rates are low, but always save something every month.

Set up a direct debit that goes into a hard to reach bank account so you cannot access it, and if you ever need cash for an urgent situation or say a deposit for a house or dental practice, you have it and you don’t have to go asking elsewhere for help.

Bottom line, start saving.

Financial-tips-for-dentist-7

Rule 8 – Get onto the property ladder

If you can afford to, and assuming you have enough savings, try and get on to the property ladder, either as a homeowner or an investor. Over time, assuming the market is rising, you should build equity in your properties which can help in many ways over the long term.

Use your income to pay off the mortgage, whilst regularly re-financing every few years seeking a better deal.

Financial-tips-for-dentist-8

Rule 9 – Pay off expensive debt

If you use a credit card pay the balance off EVERY month, DO NOT just pay the interest, pay the whole balance off.

Don’t get yourself into a situation where the interest keeps accumulating each month, this is a recipe for financial disaster as the interest rates charged are compounded each month increasing the amount you need to pay each month. At such high rates, the financial situation can get dire – so don’t’ get into such pickle in the first place by only spending what you need to spend (see rule 6)

Financial-tips-for-dentist-9

Rule 10 – Tax Free Saving

Yes, again it sounds dull, but utilise you annual ISA allowance, it’s a great way to save in a tax-free wrapper and you should try to use this every year.

Financial-tips-for-dentist-10

Rule 11 – Buy or build your own practice but be SMART

Many Dentists I meet entered the profession so they could run their own business. I strongly advocate becoming a business owner, but don’t rush it and most definitely seek advice from the right people (see rule 5 above) who can help you achieve your goal.

Keep your emotions at the door, and make a sensible purchase rather than one that is based on the emotion having to have a practice at any cost. I have seen too many dentists buy at too high a price and regret it for many years.

Be Smart.

Financial-tips-for-dentist-11

Click here to our articles Samera learning centre.

About the Author

Arun Mehra

Arun Mehra

With almost twenty years of commercial experience and knowledge in Dentistry, Arun’s expertise is valued by hundreds of businesses across the UK. His financial acumen and know-how, along with his hands-on commercial expertise have helped clients, large and small, new and established to achieve great things.

Arun is the founder of the Samera Group, starting the business with just one client sitting at his father’s dining table. Fifteen years on, Team Samera now service hundreds of Dental clients, run exciting events, help clients raise finance, and are very active in helping clients buy or sell Dental practices.

Join the Samera Alliance Buying Group

The Samera Alliance is our growing network of dentists, practices and leading industry suppliers, designed to help you save money, grow your profits and build a better dental business.

Join today for free to be a part of our dental buying group, which gives you access to exclusive discounts and offers on the consumables, equipment and products you need to run a successful dental business.

You’ll also get better rates and terms for a wide range of services like HR, IT, utilities, insurance, legal services and much more!

Business Loans for Dentists

We’ve been helping to fund the future of the UK’s dentists for 20 years and our team are made up of former bankers with decades of experience and contacts in the UK’s healthcare lending sector.

You can find out more about working with Samera Finance and the financial services we offer by booking a free consultation with one of the Samera team at a time that suits you (including evenings) or by reading more about our financial services at the links below.

Dental Practice Finance: Further Information

For more information on raising finance for your dental practice, including more articles, videos and webinars check out our Learning Centre here, full of articles an webinars like our How to Guide on Financing a Dental Practice.

Make sure you never miss any of our articles, webinars, videos or events by following us on Facebook, LinkedIn, YouTube and Instagram.